Core product focus
Micro-credit delivered strictly through the Joint Liability Group model, for first-time creditworthy women micro-entrepreneurs in rural and semi-urban centres.


Gramo Fin extends micro-credit to first-time women entrepreneurs in rural and semi-urban India — with multi-layer underwriting, geotagged field controls and board-level governance from day one.
01 / Company
A Delhi-based MFI focused on the socio-economic empowerment of women, led by an experienced executive team and commencing operations across Rajasthan, Uttar Pradesh and Haryana by November 2026.
Micro-credit delivered strictly through the Joint Liability Group model, for first-time creditworthy women micro-entrepreneurs in rural and semi-urban centres.
₹2 Cr initial equity from promoters and the Kothiwal Family Group, with a committed ₹3 Cr follow-on infusion to support multi-year scaling.
The Kothiwal Family Group is an established regional conglomerate running institutions in higher education, healthcare and financial services.
02 / Operating model
Social collateral from 5-member mutual-guarantee groups, combined with rigorous credit appraisal and mobile-enabled field controls.

Self-selected solidarity groups of five women peers. Centres are created with strict cross-guarantee screening.
Multi-day CGT covering loan terms, centre rules and financial literacy before any disbursement.
Disciplined bi-weekly or monthly routines with digital attendance and instant collections logging.
Mandatory geotagged Loan Utilisation Check within 30 days, confirming credit is deployed into revenue assets.
GPS-tagged centres, biometric thumb verification and photo uploads of assets.
Real-time CRIF/Equifax pulls, debt-cap checks, IVRS updates and grievance logging.
Bank-grade encryption, automated backups, tiered access and a 99.9% uptime SLA.
Dynamic QR codes, BBPS, UPI payment links and WhatsApp reminders.
03 / Risk governance
Credit bureau scrub. Real-time automated verification against Equifax and CRIF High Mark.
Income assessment. Cash-flow appraisal keeps EMIs well under 50% of monthly household surplus.
Demographic filtering. Residence stability checks and mandatory spouse or guarantor KYC.
Dual verification. Loan Officer appraisal, then independent Branch Manager pre-sanction check.
Post-disbursement audit. Geotagged LUC uploaded within 30 days of payout.
Internal audit wing. Surprise centre audits and quarterly reviews reporting to the Board Audit Committee.
Reviews internal audit findings and ATRs across all branches and hubs.
Portfolio quality, PAR, liquidity, ALM mismatch and state-level regulatory risk.
Executive compensation, board composition and KMP appointments.
RBI Fair Practices Code and MFIN Code of Conduct are integrated into core business applications.
04 / Five-year outlook
Business plan projections. ₹ in crore.
| Metric | Year 1 | Year 2 | Year 3 | Year 4 | Year 5 |
|---|---|---|---|---|---|
| Branches | 21 | 51 | 71 | 111 | 161 |
| Field executives | 105 | 255 | 355 | 555 | 805 |
| Active borrowers | 20,160 | 66,240 | 1,35,720 | 2,39,400 | 3,85,380 |
| Disbursement | 131.0 | 299.5 | 454.6 | 678.1 | 1,148.1 |
| Loan outstanding | 100.8 | 272.9 | 445.5 | 667.2 | 1,081.7 |
05 / Leadership
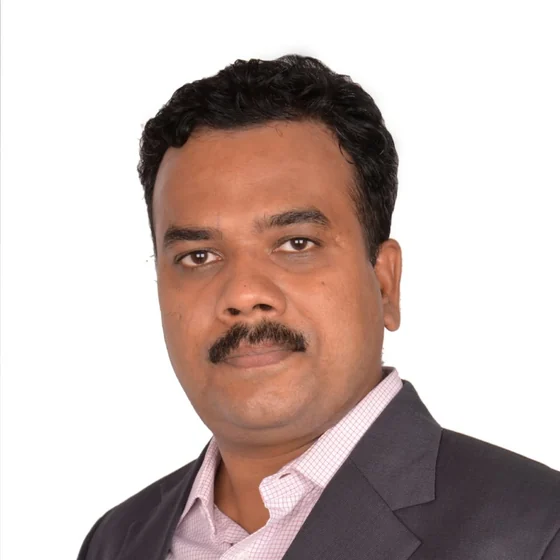
Promoter & Chief Executive Officer
Over 22 years of senior managerial experience, including 17+ years in microfinance across direct MFI and BC operations. Leadership roles at Humana Financial Services, M-CRIL, BASIX Microfinance, Intellecap, Kas Foundation and GE Capital; extensive BC track record with IDBI, Yes Bank, CSB Bank and Jana SFB.
PGDRM (XIM Bhubaneswar) · BA (JNU) · PGCPIB Investment Banking (IIM Indore)

Partner with Gramo Fin
A high-quality originating pipeline backed by institutional equity sponsorship. Active BC pipeline with Yes Bank, Jana SFB, CSB Bank and Utkarsh SFB.